
I want to start with a number, because the number tells the whole story.
The US spot bitcoin ETFs, the single biggest piece of institutional infrastructure ever built around crypto, had net-accumulated 4,500 bitcoin since the start of 2026 as of Tuesday morning. Four thousand five hundred. That is roughly $341 million at this week’s prices. Then yesterday happened. BlackRock’s IBIT alone shed $527.84 million in a single session, the second-largest daily outflow in the fund’s entire history, missing the all-time record by less than half a million dollars. The eleven US spot bitcoin ETFs combined bled $733 million on the day. More than $2 billion has now left the complex over the past two weeks. Bitcoin broke below $73,000 in Asian hours this morning after US airstrikes on an Iranian military site near the Strait of Hormuz triggered close to $1 billion in 24-hour liquidations, with 93% of those liquidations coming from long positions.
WATCH THE DAILY WOLF ON YAHOO FINANCE!
Quick note before we dig in: I'm going to be talking through all of this live today on The Daily Wolf, Yahoo Finance, 12pm ET. The only daily crypto show on mainstream financial news. 15 minutes, just me, no fluff.
The institutional bid that drove the 2025 rally is not just cooling. It is unwinding in real time. For an asset class that was supposed to be eating Wall Street’s lunch and reshaping the global financial system, the flagship vehicle for institutional bitcoin adoption has done less in five months than a single MicroStrategy purchase did in the first week of February, and is now actively running in reverse.
Meanwhile, in those same five months, the stablecoin market added roughly $50 billion in market capitalization, crossing $322 billion in total supply this week. That figure now exceeds the foreign exchange reserves of 95 countries, including the United Kingdom and Canada. Stablecoin transaction volume processed trillions of dollars in the same window. And in the last 48 hours, three of the biggest names in payments quietly walked into the door at once.
SoFi launched a national-bank-issued stablecoin to 15 million retail customers on Tuesday morning. Mastercard got a New York BitLicense Tuesday afternoon, less than three months after spending $1.8 billion to acquire a stablecoin infrastructure company called BVNK. And yesterday, the biggest one of all – Block, Jack Dorsey’s company – began rolling out USDC stablecoin payments to Cash App’s nearly 60 million users, with full availability by the end of this week.
Read that last one again. Jack Dorsey. The most prominent bitcoin maximalist still standing in mainstream tech. The man who has spent the last five years telling anyone who would listen that bitcoin was the only digital asset that mattered and everything else was a distraction. That guy. Yesterday his company switched on USDC payments for 60 million people on Solana, Ethereum, Polygon, and Arbitrum. And when CoinDesk asked him in March why he was doing it, his answer was, quote, “I don’t like that we’re going to support stablecoins but our customers want to use them.”
That sentence, from that man, in that company, in this week, is the entire story of where crypto actually is in 2026.
Here is the thing that everyone in this industry needs to sit with for a minute, because we have spent fifteen years telling ourselves a story that turns out to have been wrong about the most important part. The story was that crypto would replace the dollar. Bitcoin was the hard money that would dethrone the soft money. Ethereum was the world computer that would run a parallel financial system free of the legacy rails. Stablecoins were a bridge product, a temporary on-ramp, a training-wheels solution that would eventually become irrelevant once everyone graduated to native crypto money.
That is not what happened (yet).
What happened is that crypto built the most efficient distribution layer for the US dollar that has ever existed, and the dollar walked through the front door and took up residence. Tether and Circle alone now have more US dollar-equivalent units circulating than the FX reserves of all but a handful of countries on Earth. Tether’s holdings of US Treasury securities are at $141 billion as of Q1 2026, making it the 18th largest holder of US government debt on the planet, ahead of Germany and the UAE. Stablecoin transaction volume now rivals – and by some measures exceeds – the combined throughput of Visa and Mastercard. None of this was supposed to happen, but all of it did, and the people building it now mostly work for banks.
Let me give you the cleanest articulation of what is actually going on, in the words of the people doing it.
Anthony Noto, CEO of SoFi, in his announcement Tuesday: “People no longer have to choose between blockchain technology and regulated banking products.”
Read that sentence one more time. Because that is not a statement about crypto winning. That is a statement about banking absorbing crypto. The framing is not “we are bringing banking onto crypto’s rails.” The framing is “we are bringing crypto’s best ideas onto banking’s rails, and we are going to be the trusted entity at the center of it.” That is the entire pitch. And the customer base at SoFi alone is fifteen million people who already trust SoFi for their checking account, their savings, their lending, and their brokerage. None of them are going to need a hardware wallet. None of them are going to need to learn what a private key is. None of them are going to care which chain it lives on.
Cash App is the same story at four times the scale. Sixty million users, mostly people who do not consider themselves crypto investors at all, all about to have USDC payments built into the same app they use to send rent money to their roommate and split a dinner check with their friends. That is not crypto adoption. That is the dollar getting a software upgrade.
Mastercard’s BitLicense yesterday is the same story told from the merchant-rails side. New York has issued fewer than 50 BitLicenses in the entire eleven-year history of the regime. Mastercard now joins Coinbase, Circle, Galaxy, Anchorage Digital, and Strike on that list. The license was granted to a subsidiary called Mastercard Transaction Services (U.S.) LLC, and the explicit purpose, in Mastercard’s own words, is to “engage with evolving payment and settlement infrastructure supporting digital currencies.” Translation: Mastercard is building the rails for stablecoin settlement at scale, with regulatory cover, in partnership with the same banks that already issue Mastercard products today.
Combine those three announcements with the BVNK acquisition in March and the DTCC announcement yesterday that it is bringing tokenized stocks, ETFs, and Treasuries to the Stellar blockchain by 2027, and what you have is essentially every major node of the legacy payment, settlement, and clearing infrastructure of the United States quietly migrating itself onto crypto rails inside a single week. Not buying bitcoin. Not learning about NFTs. Migrating their actual operational infrastructure onto blockchain because the math finally works.
Now let me say something the maximalist crowd is going to hate.
This is not bad for bitcoin. It is also not bad for crypto. It is just not the story we have been telling ourselves about what crypto would become. Bitcoin’s job has always been one specific thing, which is to be the asset you hold against the dollar losing its purchasing power over time. That job does not require bitcoin to be the medium of exchange for daily commerce. It does not require bitcoin to win the payments war. It does not require any of the things the bitcoin-replaces-the-dollar crowd has been promising for fifteen years. Bitcoin can be a store of value at the same time the dollar wins the medium-of-exchange war on crypto’s own rails. Both can be true. Both probably are true. And the people who refuse to see this clearly are going to spend the next decade explaining away every quarter the stablecoin market grows by another $10 billion.
Jack Dorsey was the last major bitcoin maximalist who could credibly insist that everything else was a distraction. He just blinked. He looked at the data, he looked at his customers, he looked at the rails his own company is going to live or die on for the next decade, and he capitulated. Not on bitcoin – he still owns plenty of it, and Cash App still treats bitcoin as a strategic priority. He capitulated on the maximalist narrative that bitcoin would be the only thing that mattered. “I don’t like that we’re going to support stablecoins,” he said. “But our customers want to use them.”
That is what surrender looks like when an honest person does it. He told you the truth.
The honest read of this whole week is this. Crypto did not replace the dollar. Crypto built the dollar a better delivery truck, and the dollar is using it. The most valuable companies in crypto right now are not the ones building the next decentralized exchange or the next L2 or the next AI agent token. They are the ones issuing dollars on chain and the ones building the rails for those dollars to move. Tether earned $13 billion in profits in 2024, roughly matching Goldman Sachs, with about a hundred employees instead of fifty thousand. Circle’s stock has been one of the best-performing IPOs of the last twelve months. SoFi’s stock jumped 3.5% on Tuesday’s announcement and the company is now arguably worth more for its stablecoin product than for its lending book. Mastercard did not spend $1.8 billion on a stablecoin firm because it thought stablecoins were a fad. Block did not spend the last three years building its stablecoin integration because Jack Dorsey suddenly stopped believing in bitcoin.
The market has voted, and the vote was not even close.
If you are still positioning your portfolio around the idea that bitcoin is going to displace the dollar in everyday commerce, you are not just betting against the market. You are betting against the people who actually move the money, including the most prominent bitcoin maximalist who ever ran a public company. The banks are not coming. The banks are already here. They figured out that the cheapest way to keep being banks for the next fifty years was to put their dollars on the rails crypto built. They did not need to crush crypto to do that. They just needed to absorb it. And that absorption is what we are watching in real time, with SoFi on Tuesday morning and Mastercard on Tuesday afternoon and Cash App on Wednesday and the DTCC quietly telling the world it is putting Russell 1000 stocks on Stellar by 2027.
The dollar won the distribution war. Bitcoin still has a chance to win the store-of-value war. Those are two different wars. Smart investors are figuring out the difference. The rest are still arguing about whether stablecoin growth is bullish or bearish for crypto.
Spoiler: it is bullish for some kinds of crypto and bearish for others, and the line between those two categories is the one detail that is going to determine who actually makes money in the next decade.
I’ll see you tomorrow.
You have likely noticed a major change in the newsletter over the past few weeks - it is shorter, more focused on deep dives and the news, and less focused on markets.
As you likely know, in all of my years in trading, I tried almost everything and found myself using a single indicator with a high hit rate that I could generally rely on - bullish divergence with oversold RSI and bearish divergence with overbought RSI.
I want to show you a few charts.
The first is Bitcoin.
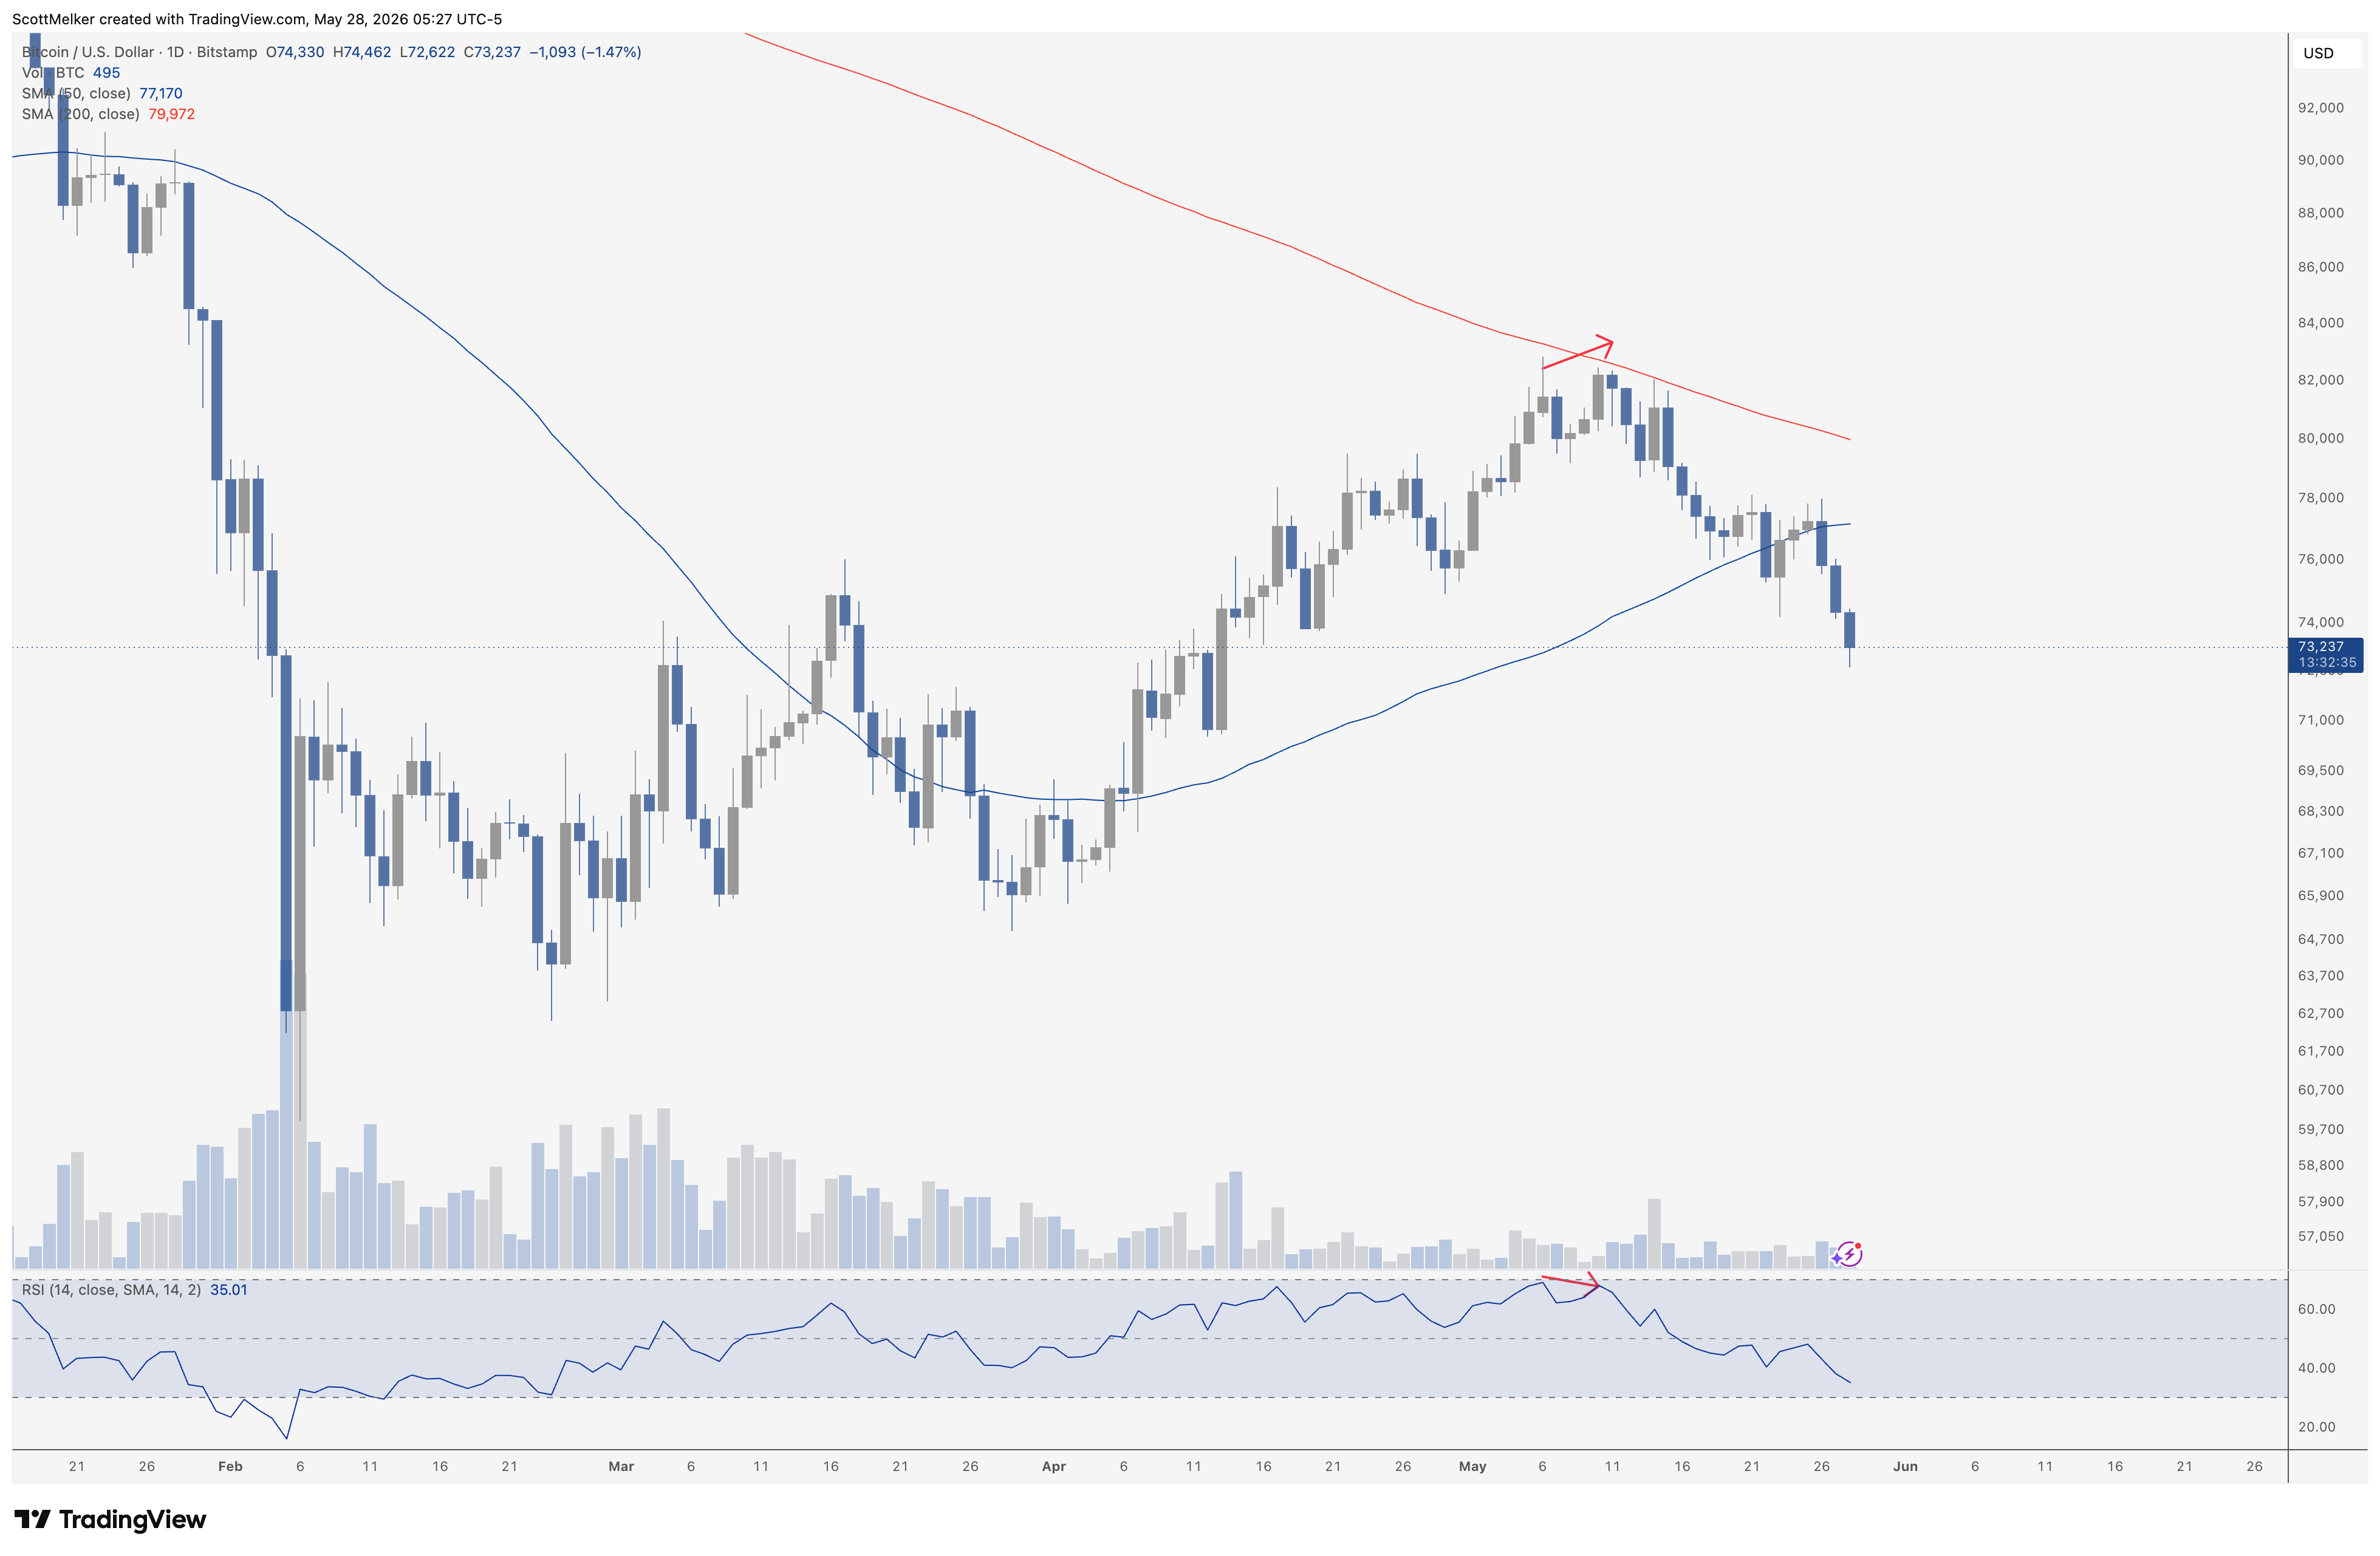
As you can see, Bitcoin printed bearish divergence (not quite overbought) on the daily chart a couple of weeks ago. This was right into the daily 200 MA, a major level of resistance. We have retreated since, and lost the 50 MA as support.
The second chart is the most “hyped” asset of the past few months.
Hyperliquid.
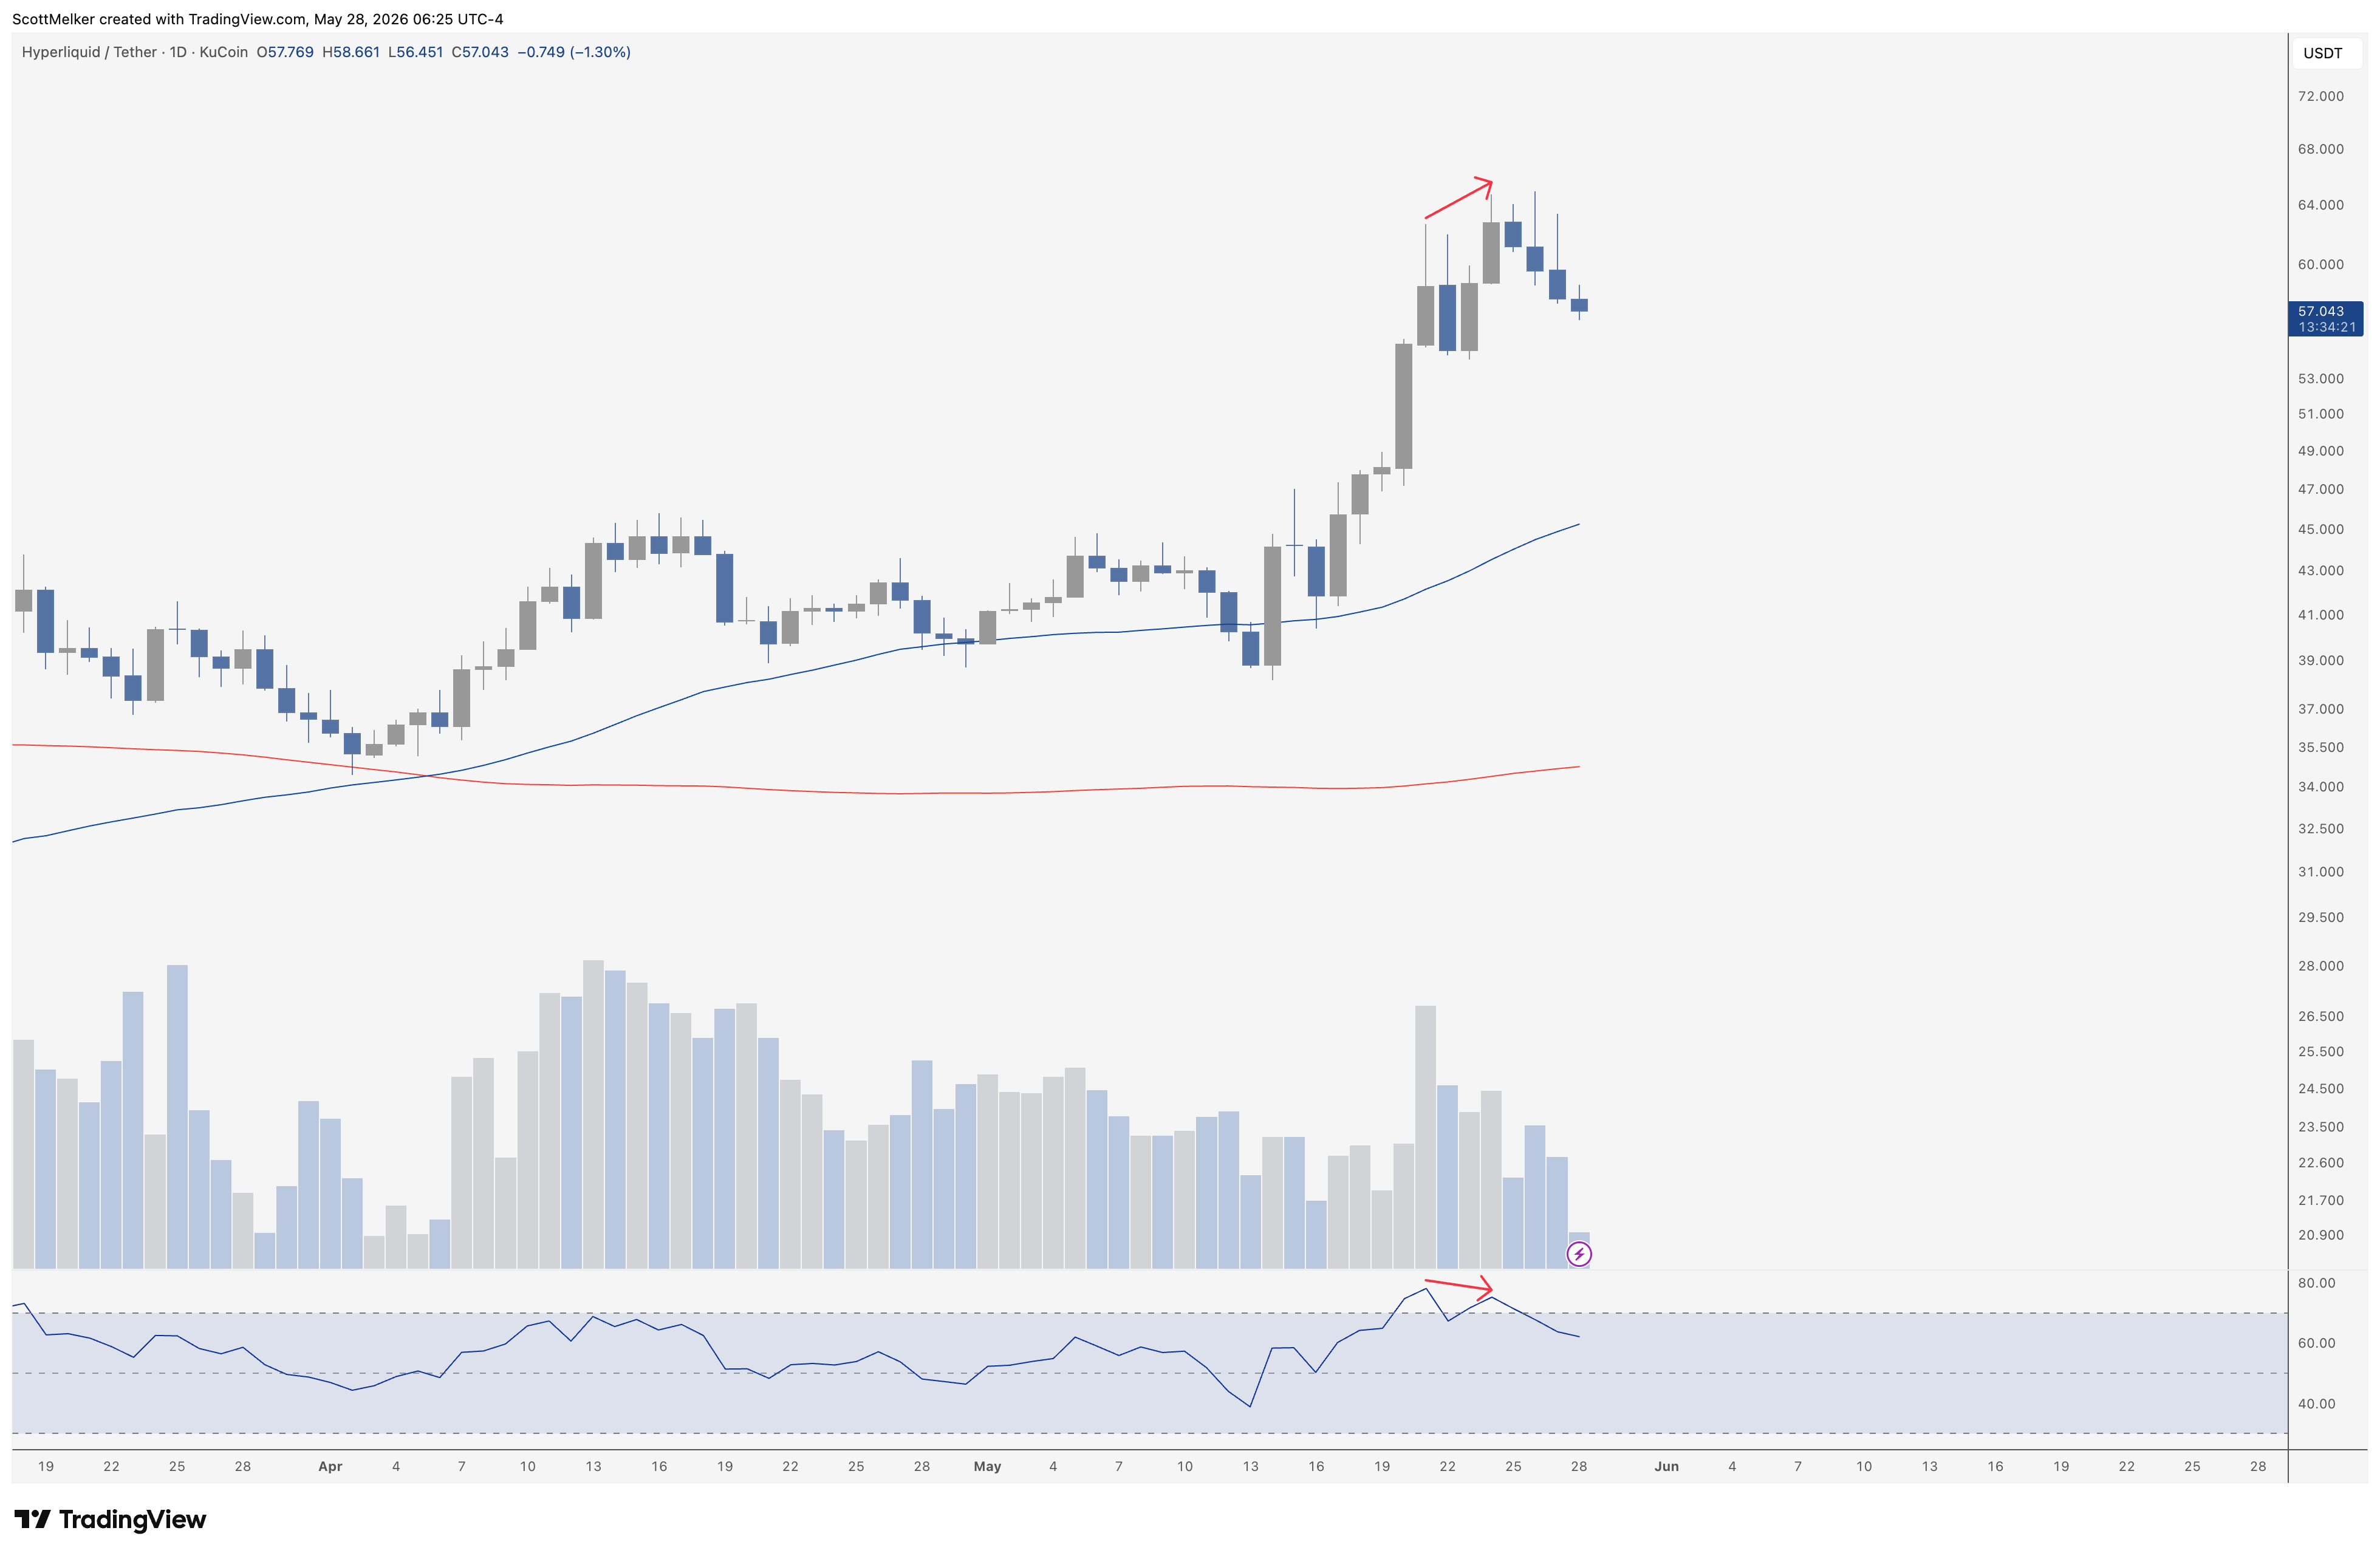
This printed bearish divergence a few days ago, with massively overbought conditions. You also likely noticed peak euphoria about this token on social media.
The final chart is ZEC, which is the other most discussed token and narrative in the crypto community.
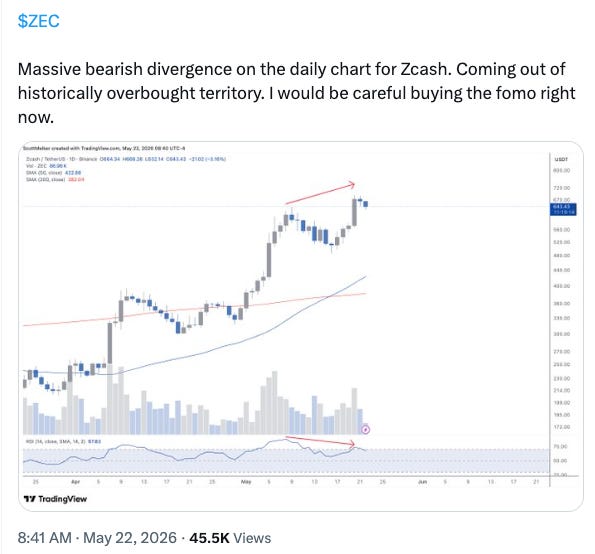
This one I chose to share days ago on X as a word of caution. You can see where we are now.
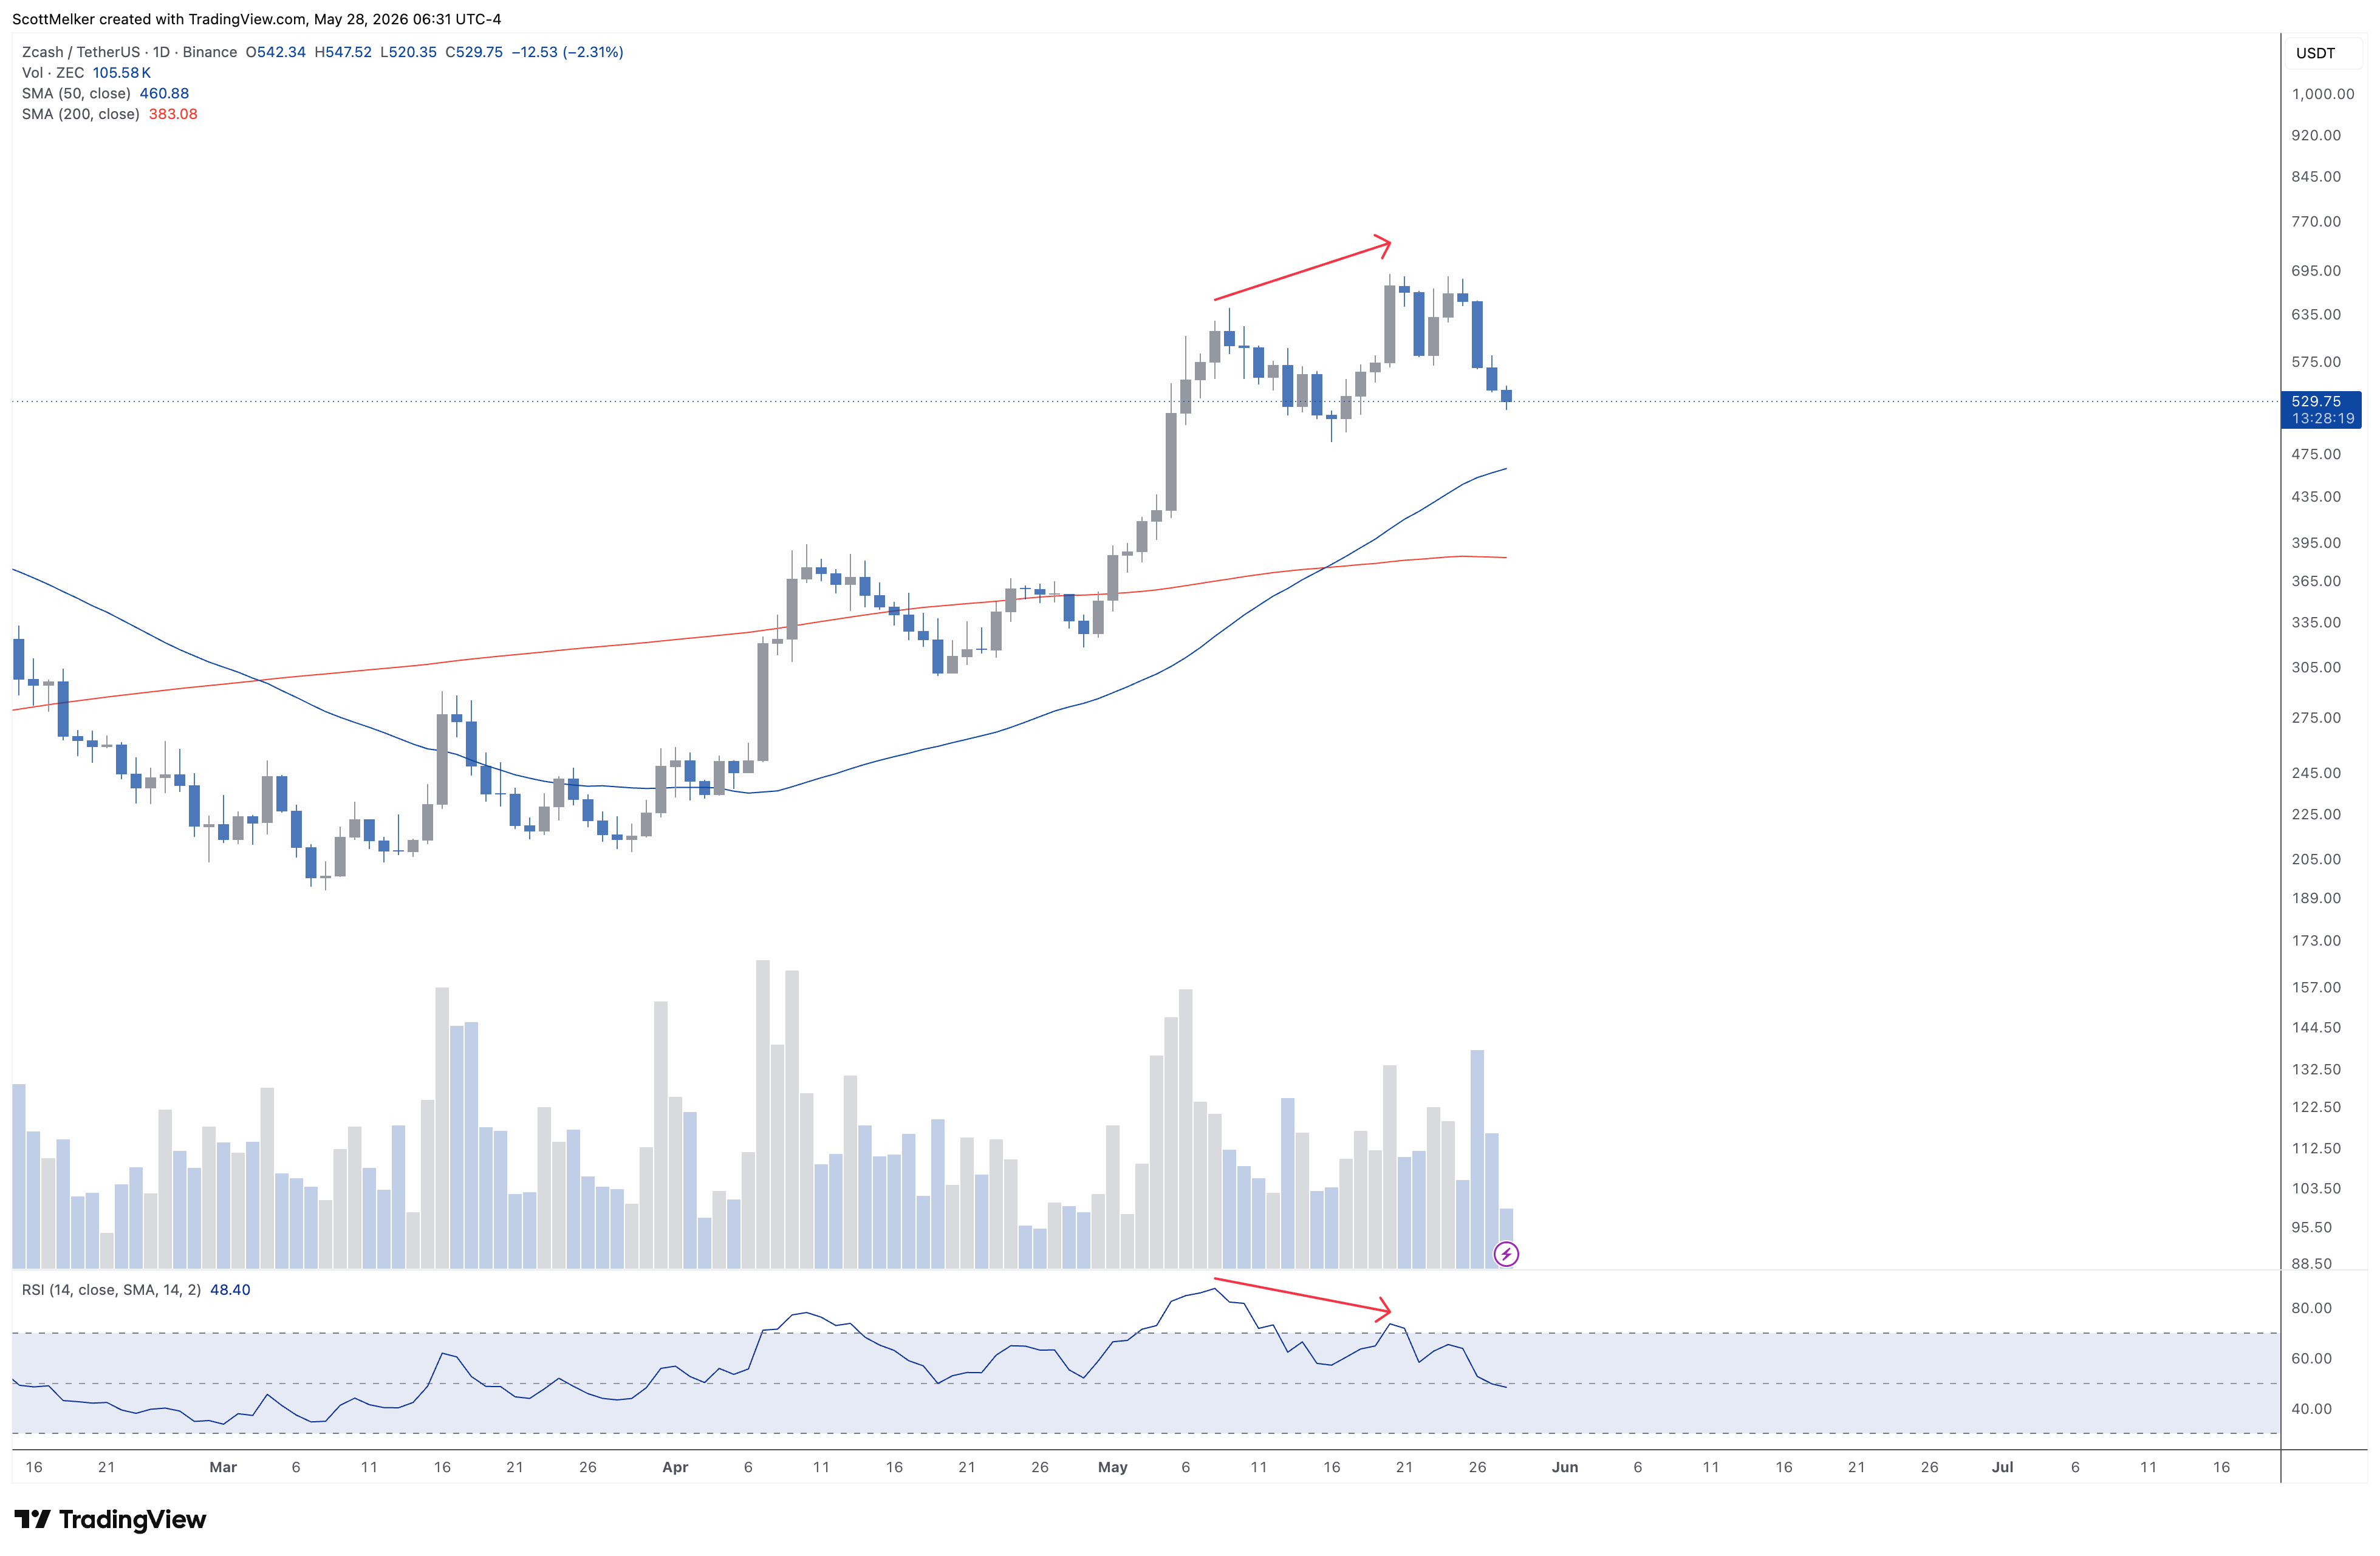
The charts of the tokens that actually have volume have been giving the same signal across the board. We had a nice bullish move, but still during a general bearish trend.
This does not mean things have to go much lower, it means that I have been cautious and will remain that way. These most likely are headed to oversold on the daily chart, which can take a while.
BlackRock’s IBIT Just Posted Its Second-Worst Day In History. Bitcoin Cracked $73,000 Overnight.
BlackRock’s bitcoin ETF sheds $528 million, the second-largest daily outflow on record
BlackRock’s iShares Bitcoin Trust shed $527.84 million in net outflows on Wednesday, the second-largest single-day withdrawal since the fund launched in January 2024, missing the all-time record set on January 30 by less than half a million dollars. The full complex of eleven US spot bitcoin ETFs lost a combined $733.43 million on the day, with Fidelity’s FBTC down $60.30 million and Grayscale’s GBTC down $104.76 million. Over the past two weeks, the entire ETF channel has bled more than $2 billion. The selling landed on the same day bitcoin broke below $73,000 in Asian trading, hitting a low of $72,912 after US airstrikes on an Iranian military site near the Strait of Hormuz reignited a conflict the market had started to price out. The IBIT outflow followed a separate eye-catching event Tuesday, when a single investor sold $1.29 billion of IBIT shares in one dark-pool block trade. The institutional bid is unwinding in real time, and the macro setup is going to get worse before it gets better.
Kraken Just Brought Bitcoin Yield Back.
Kraken Launches BTC Yield Product the Same Week Exploits and Security Warnings Mount
Kraken launched Bitcoin Vault yesterday, a new product inside Kraken Earn that pays long-term BTC holders up to 2.5% APY by routing their bitcoin through Aave and Morpho via a Veda-powered, Sentora-managed strategy on the Ink network. The structural difference from 2022 is that this is overcollateralized onchain lending instead of opaque centralized rehypothecation. The structural similarity is that retail bitcoin holders are once again being offered yield on an asset that does not natively produce any, and the underlying complexity is being abstracted away into a clean exchange UI. Aave, one of the three protocols Kraken is routing into, just absorbed $196 million in bad debt from the Kelp DAO exploit in April. Stake DAO was exploited yesterday for $91,000. The yield product is the same product. The plumbing is genuinely better. The question is whether the people opting in understand the difference, or whether “better plumbing” is what gets said right before the next cycle of customers learns the same lesson the hard way.
Bitwise’s HYPE ETF Just Became The Biggest In The World, On A Day Bitcoin ETFs Bled Again. The Rotation Is Real.
Bitwise’s Hyperliquid ETF (BHYP) recorded $19 million in single-day inflows on Tuesday, its largest day yet, vaulting it to roughly $63 million in AUM and making it the largest Hyperliquid-linked ETF in the world. HYPE hit a fresh all-time high above $64 the same day, while combined US spot Bitcoin and Ethereum ETFs have bled roughly $1.64 billion since May began. Bitwise CIO Matt Hougan said the pitch to financial advisors is “magic” because 99% of Hyperliquid’s protocol fees go to buying back HYPE, creating a continuous structural bid that no traditional crypto ETF has. The HYPE ETFs have now absorbed about 1.04% of the token’s market cap in their first ten trading days, outpacing both Bitcoin and Ether ETFs on an adjusted basis. The investors I take most seriously are the ones who can hold two ideas in their head at once: that bitcoin is the long-term institutional store of value, and that the short-term incremental flow is going where the protocol revenue actually accrues to the token. Both things can be true, and pretending the latter is not happening because it inconveniences the maximalist thesis is going to look very silly in eighteen months.
The Clearinghouse For $114 Trillion In US Securities Just Announced It Is Going On A Public Blockchain. Stop Pretending Tokenization Is Not Happening.
DTCC taps Stellar to tokenize blue chip equities, ETFs and Treasuries by 2027
The Depository Trust & Clearing Corporation, the clearinghouse that sits at the center of US market infrastructure and oversees more than $114 trillion in assets, announced yesterday that it is partnering with the Stellar Development Foundation to bring tokenized versions of Russell 1000 stocks, major ETFs, and US Treasury debt to the Stellar public blockchain by the first half of 2027. The integration follows an SEC No-Action Letter from December 2025 that cleared DTCC to begin tokenizing custodied assets, with limited production trades scheduled for July ahead of a broader rollout in October. This is not a private permissioned network. This is the central post-trade infrastructure of the United States announcing that it is going to settle Russell 1000 stocks on a public blockchain. If you are still arguing that tokenization is a crypto-industry talking point and not a structural rewiring of how Wall Street settles trades, you should probably catch up before the next eighteen months happen.
Bitcoin Just Absorbed A $1.29B BlackRock Dump & Barely Flinched
The views and opinions expressed here are solely my own and should in no way be interpreted as financial advice. Every investment and trading move involves risk. You should conduct your own research when making a decision. I am not a financial advisor. Nothing contained in this e-mail constitutes or shall be construed as an offering of financial instruments or as investment advice or recommendations of an investment strategy or whether or not to "Buy," "Sell," or "Hold" an investment.
Thanks for reading The Wolf Den! Subscribe for free to receive new posts and support my work.
Crypto was always meant to be a payment rail. Peer‑to‑peer, borderless, efficient. Somewhere along the way, speculation and “replace the dollar” narratives took over. Maybe this isn’t crypto losing, maybe it’s crypto finally doing what it was built to do.
Solid perspective 👀 The real challenge isn’t just regulation-it’s balancing innovation with clarity. Excited to see how this unfolds in the next phase of crypto.